Equity release, explained by a specialist
A lifetime mortgage lets you release money from your home, usually from age 55, without moving. But interest builds up quickly and it reduces what you leave. Beth, our CeRER-qualified advisor with 23 years in the mortgage industry, will take you through it face to face and look at the alternatives first.
← All mortgage guidesLater life & lifetime mortgages
5.0160+ Google reviews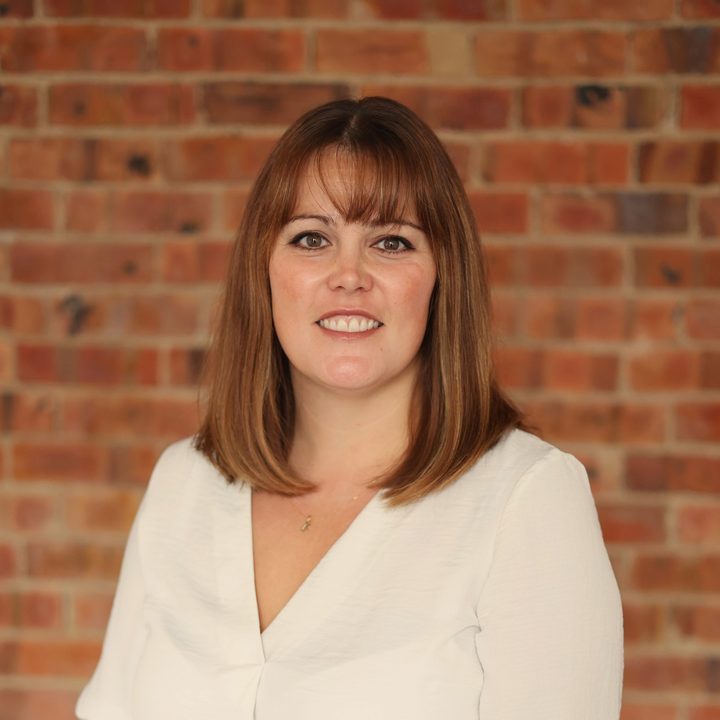
Your equity release advisor
Beth Saunders
Senior Mortgage Consultant · CeMAP, CeRER
Beth is our equity release advisor. As well as CeMAP, she holds CeRER, the Certificate in Regulated Equity Release, the specialist qualification for advising on lifetime mortgages. Ask for a call back on this page and it comes straight to her.
23 years in the mortgage industry
 Beth is a member of the Equity Release Council, the body that sets the standards for equity release. See her listing
- Face-to-face appointments with Beth at our office in Poole, or a video call if that’s easier.
- Bring your family. We encourage it, and they’re welcome at every meeting.
- More than one conversation is normal. There’s no rush and no pressure.
- She looks at the alternatives first, and checks whether it could affect any benefits you get.
- You’ll get a personalised illustration of the costs before you decide anything.
How it works
What a lifetime mortgage is
A lifetime mortgage is the most common kind of equity release. It’s a loan secured on your home, usually from age 55. You keep owning your home and can live there for the rest of your life.
Most don’t need monthly payments. Instead the interest is added to the loan, so what you owe grows over time. The loan and the interest are repaid when the last of you dies or moves into long-term care, usually from the sale of your home.
Lump sum
Take it in one go
The money is paid to you at the start. Interest is charged on all of it from day one.
Drawdown
Take what you need, when you need it
Take some now and leave the rest in a reserve to draw later. Interest is only charged on what you take, but the reserve isn’t guaranteed, and later withdrawals are at the rate at the time.
Paying interest
Keep what you owe down
Many plans let you pay some or all of the interest each month, which slows the amount owed growing or stops it. With some plans it’s part of the deal, so the payments must be kept up.
The other kind of equity release is a home reversion plan, where you sell part or all of your home to a provider. We advise on lifetime mortgages, not home reversion plans.
Equity release calculator
See how the interest builds up
Put in what your home is worth and what you’d release. It shows what you’d owe year by year, and what that leaves of your home. Tick the box to see it with your home going up in value.
Your home and the lifetime mortgage
With most lifetime mortgages nothing has to be paid each month: the interest is added to what you owe, and interest is then charged on that too. Many let you pay some of the interest if you want to, up to a limit. Rates move, and yours would depend on your age, your home and the lender, so try a few.
Your home’s value
Unticked, your home stays at today’s value. House prices can fall as well as rise, so any growth here is an assumption, not a forecast.
After 15 years
Worth knowing
At 7.50%, with nothing paid, what you owe roughly doubles every 9.3 years. Interest is charged on the interest already added. Paying some of it each month, if you can, slows this down. Try it above.
It reduces what you can leave, and it can affect means-tested benefits. Talk it through with your family. We check your benefits position as part of the advice.
Year by year: what you’d owe and what’s left
| Year | Owed | Left |
|---|---|---|
| Year 1 | £80,822 | £269,178 |
| Year 2 | £87,097 | £262,903 |
| Year 3 | £93,858 | £256,142 |
| Year 4 | £101,145 | £248,855 |
| Year 5 | £108,997 | £241,003 |
| Year 6 | £117,459 | £232,541 |
| Year 7 | £126,577 | £223,423 |
| Year 8 | £136,404 | £213,596 |
| Year 9 | £146,993 | £203,007 |
| Year 10 | £158,405 | £191,595 |
| Year 11 | £170,702 | £179,298 |
| Year 12 | £183,954 | £166,046 |
| Year 13 | £198,235 | £151,765 |
| Year 14 | £213,625 | £136,375 |
| Year 15 | £230,209 | £119,791 |
An illustration, not a quote. It assumes one fixed rate throughout and leaves out fees: any added to the loan would be charged interest too. A lifetime mortgage is usually repaid from the sale of your home when the last of you dies or moves into long-term care.
This is a lifetime mortgage. To understand the features and risks, ask for a personalised illustration. These figures are a guide, not a quote. A lifetime mortgage is a loan secured on your home, and it isn’t right for everyone, so we look at the alternatives with you first.
Before you decide
The downsides, and the protections
The downsides to weigh up
- Interest builds on interest. With nothing paid, what you owe can double in under 10 years.
- It reduces what you can leave your family, and over a long time it can use up all of your home’s value.
- It can affect means-tested benefits, such as Pension Credit.
- Paying it off in full early can mean an Early Repayment Charge, which can be large.
- It can limit your options later, for example if you want to borrow more, or move to a home the lender won’t accept.
- It’s a loan secured on your home. You’ll need to keep the home insured and in good repair, and keep to the terms of the plan.
Protections you’ll have
We only recommend lifetime mortgages from lenders that are members of the Equity Release Council. Their plans come with:
- A fixed interest rate, or a variable rate with a cap that’s set for life.
- The right to live in your home for life, or until you move into long-term care, as long as you keep to the terms.
- The right to move to another home the lender accepts, and take the plan with you.
- A no negative equity guarantee: when your home is sold, you or your estate will never have to repay more than it sells for.
- The right to make penalty-free payments, subject to the lender’s criteria.
- Your own solicitor, to give you independent legal advice before you go ahead.
Want it set out for your own home?
Beth will go through how a lifetime mortgage would work for you, what it would cost, and the alternatives.
Before a lifetime mortgage
It isn’t right for everyone
Being old enough for a lifetime mortgage doesn’t make it the right answer. Beth will look at the alternatives with you first.
Pay the interest monthly
A retirement interest-only mortgage
You pay the interest each month, so what you owe doesn’t grow. It runs until you die, move into long-term care or sell, but you need the income to afford the payments.
Retirement interest-onlyBorrow on your income
A mortgage into retirement
Some lenders will lend into later life, on repayment or interest only, based on your pension and other income.
Already have a mortgage?
Remortgage or borrow more
If you have a mortgage now, a remortgage or more borrowing may still be possible, and could cost less over time.
RemortgagingMove
Downsizing
Moving somewhere smaller or cheaper can free up money with no loan at all, though moving has costs of its own.
Other money
Savings, family and grants
Savings or other assets, help from family, or a council grant for repairs or adaptations to your home.
Benefits
Anything you’re missing
Check you’re getting any benefits you’re entitled to, such as Pension Credit. It can change how much, if anything, you need to borrow.
Buying in later life
Moving or buying a home in retirement
Downsizing, moving nearer family, or somewhere all on one level? You don’t have to buy outright. Depending on your age and income, a mortgage that runs into retirement, a retirement interest-only mortgage or a lifetime mortgage can all be used towards buying your next home.
Each works very differently, and what suits you depends on what you want to leave, what you can afford each month and how long you plan to stay. Beth will set them side by side for your own figures.
What we’ll look at with you
- What you could borrow on your pension and other income, and for how long.
- Whether paying the interest each month, or none of it, suits you better.
- What each option would leave of the new home over the years.
- The timing, if you’re selling one home and buying another.
How it works with us
From a first chat to completion
A first chat
Ask for a call back or ring us. Beth will ask what you’re looking to do, and whether family will be involved.
Meeting Beth
Face to face at our office in Poole, or by video call. Bring your family if you can: we encourage it.
Every option
Beth looks at the alternatives, your benefits and your plans for the future, not just a lifetime mortgage.
Time to think
You’ll get a personalised illustration of the costs. Take as long as you need. More than one meeting is normal.
Your own solicitor
A solicitor gives you independent legal advice before anything is signed and the money is released.
Equity release questions
What is equity release?
A way to take money from the value of your home without moving out. There are two kinds: a lifetime mortgage, which is a loan secured on your home, and a home reversion plan, where you sell part or all of your home to a provider. We advise on lifetime mortgages only, not home reversion plans.
How old do I need to be?
Usually 55 or over. How much you can release depends on the age of the youngest of you, your home and the lender. Generally, the older you are, the more you can release.
Will I still own my home?
Yes. With a lifetime mortgage your home stays yours, and you can live in it for the rest of your life, or until you move into long-term care, as long as you keep to the terms of the plan.
What happens when I die or move into care?
The loan and the interest are repaid, usually from the sale of your home. With a joint plan, that happens when the second of you dies or moves into long-term care. Your family can repay it another way if they want to keep the home, and anything left after the loan is repaid goes to your estate.
Can I pay it back early?
You can usually pay some back without a charge, up to a limit set by the lender. Paying off the whole loan early can mean an Early Repayment Charge, and it can be large. Some plans don’t charge it in certain situations. Beth will go through exactly when it would apply.
Will it affect my benefits?
It can. Having the money could affect means-tested benefits, such as Pension Credit or Council Tax Reduction. Beth will check whether it could affect anything you receive before you decide.
Can I move house?
Plans from Equity Release Council members let you move to another home and take the plan with you, as long as the lender accepts the new home. If it’s worth less, you may need to repay some of the loan.
Should my family be involved?
You don’t have to involve them, but we encourage it, as it affects what you leave them. They’re welcome at every meeting, whether that’s in our office or on a video call.
Where would we meet?
Face to face at our office at 26 Parkstone Road in Poole, with parking at the rear, or by video call if that’s easier. Most people have more than one conversation with Beth before deciding, and there’s no rush.
What does it cost?
As well as the interest, there are usually lender fees, a valuation and legal fees. Some can be added to the loan, where they’d be charged interest too. Beth will explain every fee, including any for our advice, before you commit to anything.
Can I use it to buy a home?
Some lenders offer a lifetime mortgage towards a purchase, and a retirement interest-only mortgage or a mortgage that runs into retirement can work too. More on buying in later life.
Google reviews
What clients say about Beth
Reviews clients have left about Beth for all kinds of mortgages, not only equity release.
Worked Really Hard
I’ve recently worked with Beth! She was an absolute star! Helped me every step of the way! No such thing as a silly question and was incredibly helpful! Definitely recommend to anyone looking for a mortgage advisor. Thank you again Beth!
I Recommend Barrett
I couldn't recommend Barrett highly enough. They are professional, prompt, knowledgeable and a pleasure to deal with. My circumstances were not 'standard' but Beth's knowledge was second to none and she made the whole process easy. Thanks to all at Barrett for a great service and for helping me get the best mortgage.
Best Broker Ever
The best broker I have ever come across, Beth is a credit to this profession. Always goes above and beyond to provide an excellent service, buying a house can be stressful but Beth really explains everything and is always on hand to provide answers to queries. I have been lucky to have worked with Beth on a number of applications and couldn't recommend her highly enough. Thanks for all your assistance.
More on equity release
Retirement Interest-Only Mortgages
Understanding Retirement Interest-Only Mortgages
Equity ReleaseYou Should Consider a Lifetime Mortgage If…
Where lifetime mortgages and equity release may be suitable
Equity ReleaseYou May Not Need a Lifetime Mortgage If…
Why lifetime mortgages and equity release may not be suitable
Talk to Beth about equity release
Leave your name and number and Beth will call you back for a first chat, and to arrange a face-to-face appointment at our office if you’d like one. Family are welcome. No long forms, and no pressure.
Beth Saunders, CeMAP & CeREROur equity release advisor, 23 years in the mortgage industry
- Rated 5.0 from 160+ Google reviews
- Calls answered in 22 seconds on average
- Open Monday to Saturday, 9am to 5pm