Mortgage advice for Bournemouth, from an office ten minutes away
Independent advice from our office on Parkstone Road, Poole. Student HMOs, town centre flats, holiday lets, period houses and new builds — we have access to the whole of the intermediary market.
5.0160+ Google reviews
Where we are, who we act for
Ten minutes from the pier, and clients all over the UK
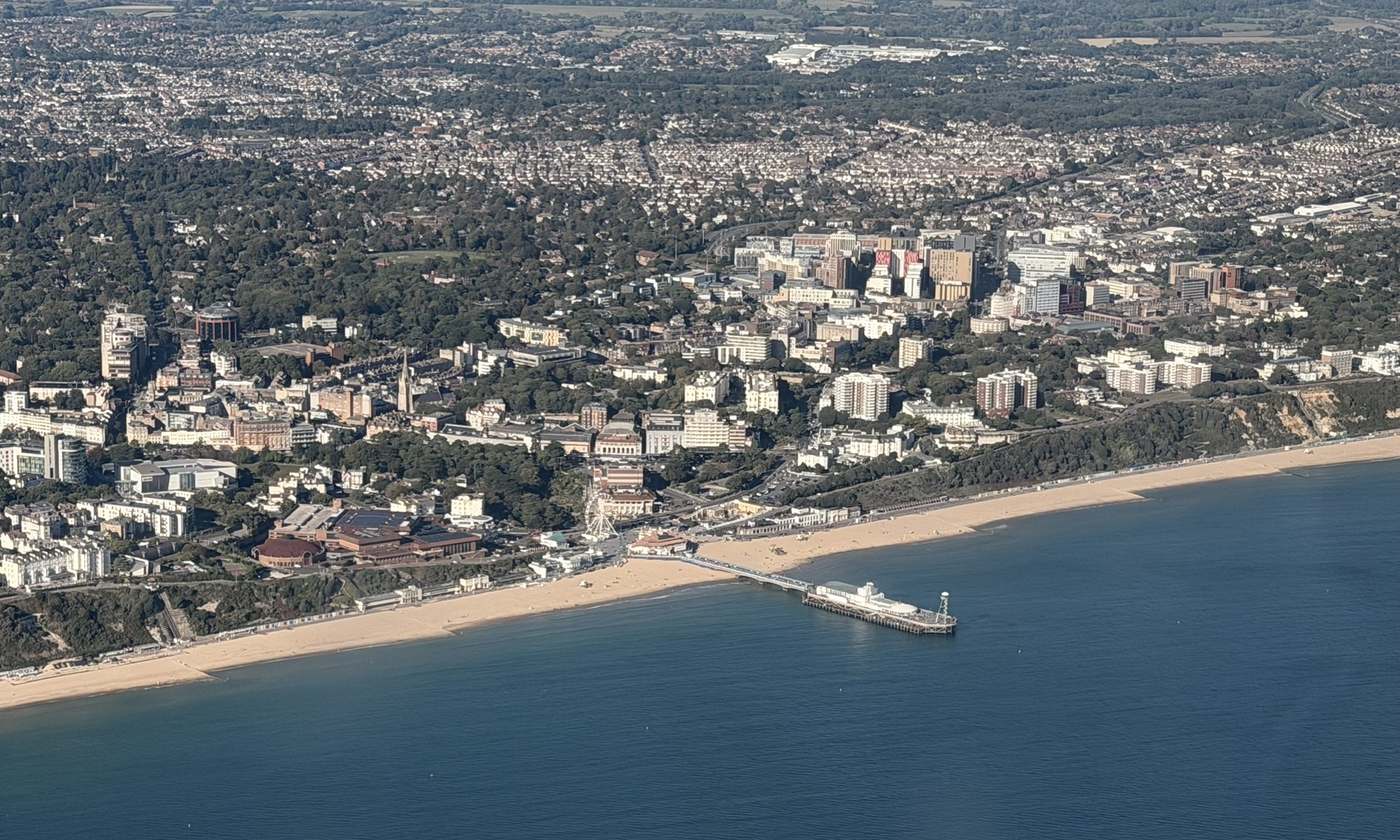
We are a Poole firm that has worked across Bournemouth for more than fifteen years. Our office is a short drive from the town centre, and most mortgages are arranged by phone, video and email wherever you live.
Bournemouth is a more varied market than it looks from the outside. Two universities and a hospital driving shared housing in Winton and Charminster; leasehold flats and taller blocks through the town centre and Westbourne; holiday lets along the seafront at Boscombe and Southbourne; large period houses in Talbot Woods and Meyrick Park; and a steady stream of buyers moving down from London. Lenders treat every one of those differently.
Local property, real lending
What we see in Bournemouth, and what it means for your mortgage
Each of these is something we deal with regularly here, and the lending point it raises.
Student and professional HMOs
Winton, Charminster, Boscombe, Springbourne
Two universities, the hospital and the colleges keep shared housing in constant demand, and a lot of local landlords own one or two. Most high-street lenders will not touch an HMO. The specialists that do want to see the licence, cap the number of lettable rooms, and above a certain size value the property on its rental income rather than on what the house next door sold for. Where an Article 4 direction applies, converting a family house needs planning permission — worth checking with BCP Council before you commit.
What we do: We work out before you offer whether the property is lendable as an HMO, and at what rate.
Town centre and seafront flats
The town centre, Westbourne, East Cliff, Boscombe
Flats are where deals fall over late. Lenders set a minimum lease length and most want a good number of years left at the end of the mortgage term, not just today. Ground rent clauses that double, flats above shops, bars or takeaways, and taller blocks needing building-safety paperwork all narrow the list sharply — and Bournemouth has plenty of all three.
What we do: We ask for the lease and the block details at the start, not at valuation, and pick a lender whose criteria they actually meet.
Holiday lets and short lets
Boscombe, Southbourne, the seafront
A standard buy-to-let mortgage does not cover a property let out by the week, and doing it anyway breaches the mortgage conditions. Holiday-let lenders are a smaller group, mostly building societies. They assess affordability on an average of low, mid and high season rates, usually from a letting agent’s projection, and most want you to already own your own home.
What we do: We match the property to the handful of lenders who want it, and sense-check the income projection before it goes in.
Period houses and conversions
Talbot Woods, Meyrick Park, Queen’s Park
The large Victorian and Edwardian houses are some of the best stock in the town, and also the most likely to throw up a surprise: flying freeholds, previous conversions, single-skin extensions, and valuations that come in below the asking price because so few directly comparable properties sell.
What we do: We line up a lender comfortable with the property type before the valuation, so a down-valuation does not end the purchase.
Ex-local authority and non-standard construction
West Howe, Kinson, Townsend
There is a lot of sensible, affordable family housing across these areas and most of it is straightforward. Where it is not, it is usually the construction type or ex-council flats: some lenders restrict flats in blocks above a certain height or want a proportion of the block privately owned, and non-standard construction cuts the lender list right down.
What we do: We identify the construction type before the application, so the valuation is not the first time anyone looks at it.
Buy-to-let and portfolios
Across the town
Student, professional and family rental demand all sit side by side here, which is why so many local landlords hold Bournemouth stock. Once you have four or more mortgaged buy-to-lets you are a portfolio landlord and the rules change: the lender stress-tests the whole portfolio, not just the property you are buying, and wants a schedule of properties plus usually a business plan and cashflow. Holding in your own name or in a limited company changes both the tax position and the lender choice.
What we do: We look at the whole portfolio before recommending the next mortgage, and work with your accountant on the ownership question rather than around them.
New builds
Town centre regeneration and Winton
Three things catch people out. Mortgage offers have a shelf life, and on a flat that completes later than expected the offer can expire before the keys appear — some lenders extend, some re-underwrite. Builder incentives such as a paid deposit, paid stamp duty or upgrades are reported to the lender and, above a limit, reduce what it will lend. And lenders cap the loan-to-value more tightly on new build flats than on houses.
What we do: We pick a lender whose offer period fits the build timetable, and get the incentives declared properly up front.
Buying from out of the area
London and commuter buyers
Bournemouth is a direct train from Waterloo, and a lot of buyers here are moving down, buying a second place, or keeping a property up the line. That usually means two mortgages in the affordability, and it often means income that a high-street calculator handles badly — bonus-heavy, self-employed, or paid through a company.
What we do: We run the affordability across both properties and place the income with a lender that actually understands it.
Armed Forces buyers
Hamworthy, Wool and Blandford
With Royal Marines at Hamworthy, the camps at Wool and Bovington and Blandford Camp all within reach, we look after a lot of serving personnel locally. Forces Help to Buy is accepted by lenders, but not all treat it the same way: the monthly repayment comes out of your affordability, and some lenders count more of your allowances and supplements as income than others. Postings are the other thing — buying somewhere you may be posted away from usually means planning for it to be let out later.
What we do: We pick a lender that treats service income and the Forces Help to Buy repayment properly, and set the mortgage up so a future posting does not cause a problem.
And the ordinary ones
Everywhere in between
Most of what we do is not unusual: first-time buyers across Bournemouth, families moving up, remortgages coming off a fixed rate, and people reshaping a mortgage for the last stretch. Commercial lending, bridging and second charge loans go through trusted packagers where that is the right answer.
What we do: Same approach either way: access to the whole of the intermediary market, one advisor, and a straight answer about what you can borrow before you go looking.
What it costs to buy here
Local prices, and the deposit behind them
Average sale prices across Bournemouth, Christchurch and Poole, from the Land Registry’s own figures.
As a rough guide on deposits: 5% is enough for many first-time buyer lenders on a house, 25% is the usual starting point for buy-to-let, holiday lets and larger HMOs ask for more, and new build flats are often capped at a lower loan-to-value than houses.
Check a monthly paymentONS and HM Land Registry, Bournemouth, Christchurch and Poole, July 2026.
The number people underestimate
Stamp duty at local prices
First-time buyers pay nothing up to £300,000 and lose the relief entirely above £500,000 — worth knowing before you stretch on an offer.
Buying any additional property adds a 5% surcharge on the whole price, and non-UK residents add a further 2%.
Work out your stamp dutyEngland and Northern Ireland rates for UK residents, at today’s rates. Examples only — check your own figure on the calculator.
A case we have done
An unlettable house turned into a five-bedroom HMO
A client wanted a four-bedroom house with two reception rooms that needed significant refurbishment. In that condition it was unlettable, which also made it unmortgageable — no buy-to-let lender would lend on it as it stood. He wanted to buy through a limited company, using deposit funds from his other trading company, and turn it into a quality five-bedroom HMO.
We raised a bridging loan to buy it and to leave enough in the transaction for the full refurbishment. With bridging, the exit is what matters most, and the exit here was a limited company buy-to-let HMO remortgage — a lender who would lend against the higher value after the works and against the rent from five lettable rooms, rather than what the house was worth on day one. That let him take most of his own money back out and move it into the next one.
Every case is different and nothing here is a promise of the same outcome. There is a second case, on a Sandbanks second home placed against company net profit, on our Poole page.
How it works from here
Have your last three months’ payslips and bank statements ready (or two to three years’ accounts if you are self-employed), plus ID, proof of deposit and details of any existing mortgages. That is enough for us to give you a real figure rather than an estimate.
Chat with a Specialist
Who will guide you through the qualification process. During our initial consultation, we aim to provide an idea of your maximum loan amount, monthly payments, and associated costs where possible, while answering any questions you may have.
Schedule a callbackFind your solution
Once we have found your solution one of our dedicated advisors will compare all suitable products and prepare your mortgage application. We’ll then handle the submission and work towards securing your formal mortgage offer.
Get my mortgage planTurn Your Dream into Reality
We’ll make the final steps as smooth as possible, coordinating with lenders to ensure a seamless process—ready for you to get the confirmation to your new venture!
Get startedWhy choose Barrett Mortgages?
Mortgage Solutions Tailored To You
At Barrett Mortgages we specialise in finding a mortgage solution that suits you, your circumstances and your lifestyle. We utilise our years of expertise and work with you to find you the right mortgage.
Flexible Finance Options
We understand that finances look different for everyone, so we are committed to helping you find a finance option that empowers you.
Full Support
Our experienced advisors will support you until the acquisition is complete, ensuring that you are fully informed throughout the process. Never hesitate to give us a call!
Come and see us
26 Parkstone Road, Poole, BH15 2PG
Ten minutes from Bournemouth town centre. Monday to Saturday, 9am to 5pm. Customer parking at the rear, off Seldown Lane — use BH15 1UA.
One advisor from the first call to completion, and the same person when your deal is coming to an end. Most clients never need to come in, but you are very welcome to.
Mortgage questions we get asked in Bournemouth
Are you based in Bournemouth?
Our office is in Poole, ten minutes down the road, and we have advised clients across Bournemouth for over fifteen years. Most of what we do is by phone, video and email wherever you are — and you are very welcome to come in. More about the office.
Can you arrange a mortgage on a student HMO near the universities?
Yes. HMOs need a specialist buy-to-let lender rather than a high-street one, and the licence, the number of lettable rooms and the valuation basis all matter. We check whether the property is lendable as an HMO before you commit. More on buy-to-let.
I’m buying a flat in the town centre. What should I check first?
The lease length, the ground rent clause, whether there is commercial space in the building, and — on taller blocks — the building-safety paperwork. Any one of those can rule out a lender. Send us the details early and we will tell you where it can go.
Can I get a mortgage on a holiday let in Boscombe or Southbourne?
Yes, but not on a standard buy-to-let mortgage. Holiday-let lenders assess the income across low, mid and high season, usually from a letting agent’s projection, and most want you to already own your own home.
I’m buying from London — does that make it harder?
No, we do it regularly. The main things are affordability across both properties if you are keeping one, and making sure your income is placed with a lender that understands how you are paid.
How much do you charge?
There will be a fee for this advice. The exact amount depends on your circumstances, but we estimate it will be £395 and it is only payable on completion of the loan. The first conversation costs nothing.
Click. Chat. Complete!
Click now to connect with our team. After discussing your circumstances, we’ll recommend the best path to completion.