Mortgage advisors for all of Dorset
From Christchurch to Lyme Regis, Silton to Portland, and everywhere in between. Thatched and listed homes, agricultural ties, holiday lets, new builds and every kind of income, with access to the whole of the intermediary market.
5.0160+ Google reviews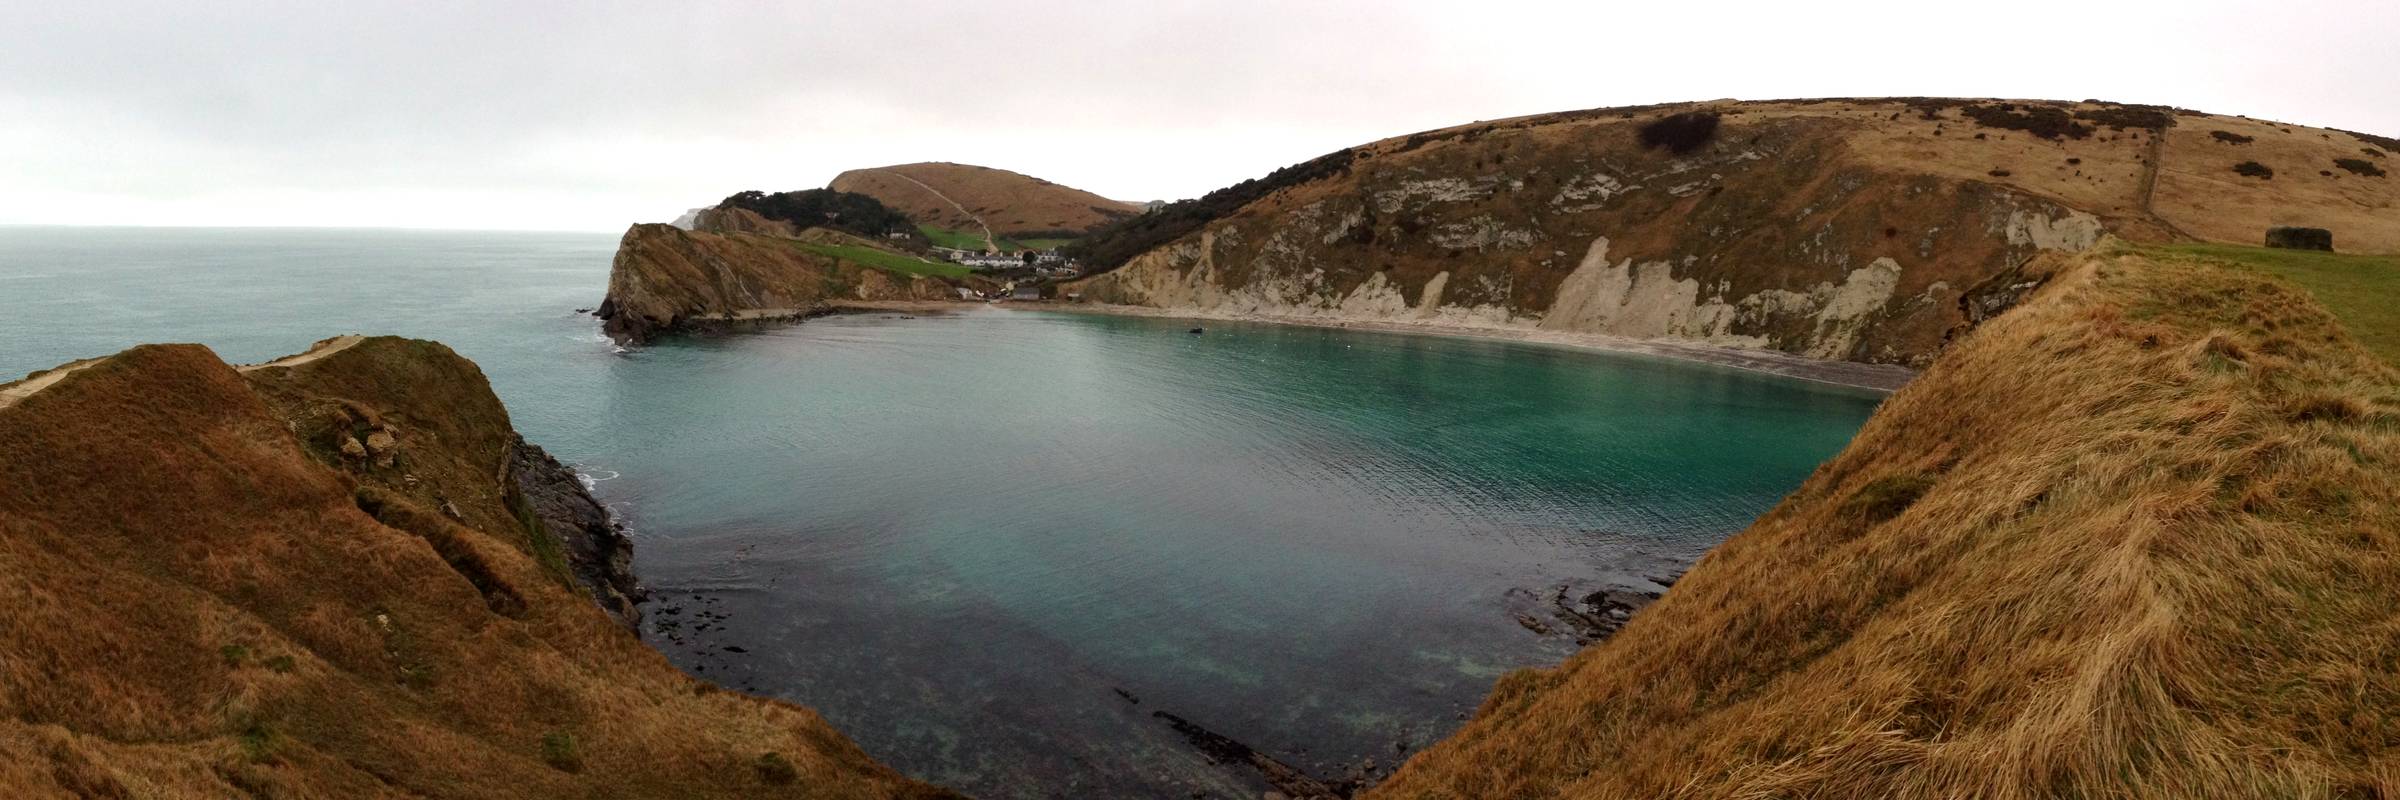
Dorset is home
A Poole office, with clients all over the county
When people think of Dorset they tend to picture the west and the Jurassic Coast. Being in Poole, Dorset is simply home, and our clients come from every part of it.
What stands out is the variety. Simple brick and tile, stone and thatch, listed cottages up to Grade I, timber-framed houses and new build flats, sometimes all in the same village. The people are just as varied: shopkeepers in the market towns, farmers, manufacturers, dog walkers in the Purbecks, yacht salesmen in Poole and mariners. Each one is a different case for a lender, and the rural parts of the county in particular throw up properties that take real work to get across the line.
Buying in Poole or Bournemouth? They have pages of their own.
Where our clients are
From one corner of the county to the other
We have arranged mortgages right across the county: the coast and the market towns, the villages, and the farms in between.
Whether you are in Weymouth, Shaftesbury or Wimborne, or somewhere much smaller, everything can be done by phone, video and email, with one advisor from the first call to completion.
Tell us where you’re buyingThe four corners
The bigger towns, and every village in between
Dorset property, real lending
What we see across Dorset, and what it means for your mortgage
Each of these is something we deal with regularly around the county, and the lending point it raises.
Thatch, stone and listed buildings
West Dorset, the Blackmore Vale, the Purbecks
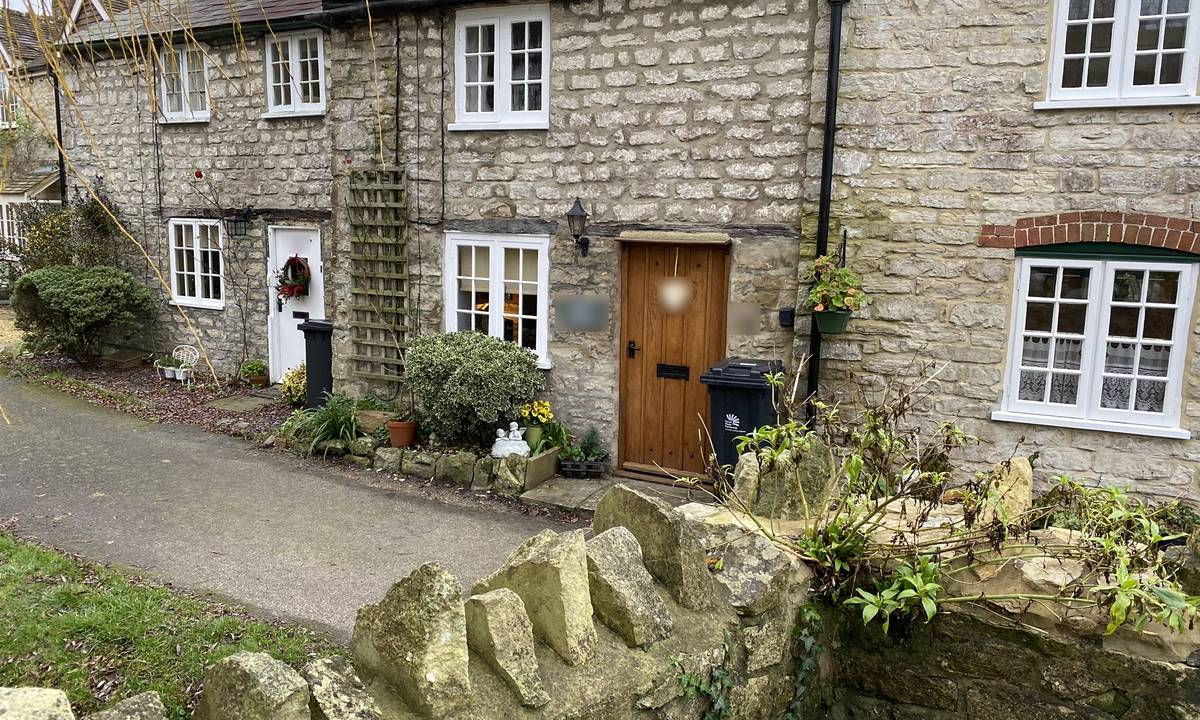
Dorset has a remarkable amount of old stone and thatch, much of it listed and some of it Grade I. Lenders treat each of these differently. Thatch usually needs a condition report and buildings insurance arranged before the offer, and that insurance costs more. The list of lenders gets shorter as the listing grade goes up, past alterations need listed building consent behind them, and older solid-wall or cob construction can mean a specialist survey.
What we do: We put the case to lenders comfortable with the age and type of the property before the valuation, and tell you up front what paperwork they will ask for.
Agricultural ties
Rural west Dorset and beyond
In parts of rural west Dorset it is not unusual for a house to carry an agricultural occupancy condition: a planning restriction on who can live there, usually people working, or last working, in farming or forestry, and their families. Lenders are restrictive. Plenty will not consider these properties at all. Those that do want to know whether you meet the condition, and value the house with the tie in mind, which usually means below the same house without one.
What we do: We have got these across the line for many clients. We read the exact wording of the condition first, then go to the lenders that will consider it.
Land, outbuildings and rural extras
Villages and farmland across the county
Rural homes rarely come as just a house. Most residential lenders lend on the home and a limited amount of land, and may give little or no value to stables, barns and paddocks. Annexes, septic tanks and private drainage, a borehole instead of mains water, shared drives and rights of way all come up at valuation. Homes near rivers or the coast need buildings insurance arranged early.
What we do: We ask about land, annexes, drainage and access at the start, so the lender sees the whole property before the surveyor does.
Timber frame and non-standard construction
Across the county
Modern timber-framed houses are accepted by most lenders. Older timber frame, concrete and steel-framed homes and prefabs are classed as non-standard construction, and the lender list shrinks sharply. Some want a structural engineer’s report; some will not lend at all.
What we do: We find out how the property is built before the application, so the valuation is not the first time anyone looks at it.
Holiday lets and second homes
Lyme Regis, West Bay, Lulworth, Weymouth, Swanage
When people think of Dorset they think of the coast, and so do buyers looking for a holiday let or a second home. A standard buy-to-let mortgage does not cover a property let out by the week. Holiday-let lenders assess the income across low, mid and high season, usually from a letting agent’s projection. A second home is a residential mortgage, with both mortgages counted in the affordability. Dorset Council has charged double council tax on second homes since April 2025, unless the property qualifies for business rates as a holiday let.
What we do: We match the property to the lenders who want it, and give you the stamp duty and running costs before you commit.
New builds and new build flats
Around the larger towns
New estates and flats have gone up around most of the bigger towns. Mortgage offers have a shelf life, and on a plot that completes late the offer can run out before the keys appear. Builder incentives are reported to the lender and, above a limit, reduce what it will lend. New build flats are often capped at a lower loan-to-value than houses.
What we do: We pick a lender whose offer period fits the build timetable, and get the incentives declared properly up front.
Self-employed, seasonal and family businesses
Market towns, farms and the Purbecks
Dorset’s working life is as varied as its houses: shopkeepers in the market towns, farmers, manufacturers running their own companies, trades, and one-person businesses like dog walkers in the Purbecks. A lot of trade is seasonal, and farm and partnership accounts can swing from one year to the next. Most lenders want two years’ figures, some will work from one, and some look at a company’s profit rather than what the director draws.
What we do: We find the lender whose way of reading your income suits it. For a guide figure first, try our self-employed mortgage calculator.
Commission, contracts and time at sea
Boat sales in Poole, mariners and engineers
Selling yachts in Poole, like plenty of other jobs, means a basic salary plus commission or bonus, and lenders differ on how much of that they count: some average it over one or two years, some take only part of it. Mariners raise their own questions: long tours away, pay from an overseas employer or in another currency, and income that does not look like a standard payslip.
What we do: We place the case with a lender whose rules suit how you are actually paid.
Armed Forces buyers
Bovington, Wool, Blandford Camp and Hamworthy
With the camps at Bovington and Wool, Blandford Camp and the Royal Marines at Hamworthy, we look after a lot of serving personnel. Forces Help to Buy is accepted by lenders, but not all of them treat it the same way: the monthly repayment comes out of your affordability, and some lenders count more of your allowances as income than others. Postings are the other thing: buying somewhere you may be posted away from usually means planning for it to be let later.
What we do: We pick a lender that treats service income and the Forces Help to Buy repayment properly, and set the mortgage up so a future posting does not cause a problem.
And the ordinary ones
Everywhere in between
Plenty of Dorset is simple brick and tile, and most of what we do is not unusual: first-time buyers in Weymouth and Dorchester, families moving up in Wimborne and Shaftesbury, remortgages coming off a fixed rate, and people reshaping a mortgage for the last stretch.
What we do: Same approach either way: access to the whole of the intermediary market, one advisor, and a straight answer about what you can borrow before you go looking.
Got an unusual property in mind?
Tell us about it before you make an offer. A CeMAP-qualified advisor will tell you which lenders will consider it, and what they will ask for.
What it costs to buy here
Dorset prices, and the deposit behind them
Average sale prices across the Dorset Council area, which is the county outside Bournemouth, Christchurch and Poole, from the Land Registry’s own figures.
As a rough guide on deposits: 5% is enough for many first-time buyer lenders on a house, 25% is the usual starting point for buy-to-let, holiday lets often ask for more, and new build flats are often capped at a lower loan-to-value than houses. For Bournemouth, Christchurch and Poole prices, see our Poole page.
Check a monthly paymentONS and HM Land Registry, Dorset Council area, July 2026.
The number people underestimate
Stamp duty at Dorset prices
First-time buyers pay nothing up to £300,000 and lose the relief entirely above £500,000.
Buying any additional property, including a second home or a holiday let, adds a 5% surcharge on the whole price, and non-UK residents add a further 2%.
Work out your stamp dutyEngland and Northern Ireland rates for UK residents, at today’s rates. Examples only — check your own figure on the calculator.
Want to know what you could borrow?
A CeMAP-qualified advisor will give you a real figure, based on your income and the property you have in mind. There’s no obligation.
From our clients
When it wasn’t straightforward
Clients whose cases needed more than a quick search, in their own words on Google.
I Cannot Recommend Darren
I cannot recommend Darren and his team at Barrett Mortgages enough, they helped us during a recent house purchase and went above and beyond what was required. My partner and I have different types of employment but where other brokers reached their limits, Darren was able to make the whole process really easy. They were extremely competent and knowledgeable, working fast and keeping us in the loop at all times, always ready to answer any questions within 24hrs. This took away a lot of the stress usually involved in these situations and made us feel more confident about the step we were about to take.
Gled Toward, Amazing
Our broker Glen Toward from Barrett Mortgages was super cool, assisted with our mortgage where other brokers lacked knowledge, he assisted in attaining the best deal, kept us updated promptly, dealt with the whole process in a very professional manner, service level is A* super smooth transaction, email replies super fast, phone calls, updates from start to end bang on, thank you Glen.
Glen Was On Time
Used Glen to help us with our remortgage. He managed to do what two other brokers could not. Great service and carried out swiftly which was great as we were up against a time frame. I will definitely use him again and would highly recommend his services to anyone.
Why choose Barrett Mortgages?
Mortgage Solutions Tailored To You
At Barrett Mortgages we specialise in finding a mortgage solution that suits you, your circumstances and your lifestyle. We utilise our years of expertise and work with you to find you the right mortgage.
Flexible Finance Options
We understand that finances look different for everyone, so we are committed to helping you find a finance option that empowers you.
Full Support
Our experienced advisors will support you until the acquisition is complete, ensuring that you are fully informed throughout the process. Never hesitate to give us a call!
Every advisor is CeMAP qualified Equity release advice from a CeRER-qualified advisor Meet the team
How it works from here
Have your last three months’ payslips and bank statements ready (or two to three years’ accounts if you are self-employed), plus ID, proof of deposit and details of any existing mortgages. For a rural or unusual property, the estate agent’s details and anything you know about the land, the construction or any planning conditions help too.
Chat with a Specialist
Who will guide you through the qualification process. During our initial consultation, we aim to provide an idea of your maximum loan amount, monthly payments, and associated costs where possible, while answering any questions you may have.
Schedule a callbackFind your solution
Once we have found your solution one of our dedicated advisors will compare all suitable products and prepare your mortgage application. We’ll then handle the submission and work towards securing your formal mortgage offer.
Get my mortgage planTurn Your Dream into Reality
We’ll make the final steps as smooth as possible, coordinating with lenders to ensure a seamless process—ready for you to get the confirmation to your new venture!
Get startedMortgage questions we get asked across Dorset
Do you cover the whole of Dorset?
Yes, from Christchurch to Lyme Regis and from Silton to Portland. Our office is in Poole, and everything can be done by phone, video and email, so it makes no difference where in the county you live. You are welcome to come into the office if you would like to.
Can I get a mortgage on a house with an agricultural tie?
Often, yes, but with fewer lenders. Plenty will not consider a property with an agricultural occupancy condition. Those that do want to know whether you meet it, and value the property with the tie in mind. It is common in parts of rural west Dorset, and we have got many of these across the line. Send us the wording of the condition and we will tell you where it can go.
Will lenders lend on a thatched or listed property?
Many will, each with its own conditions: usually a thatch condition report, buildings insurance in place before the offer, and more caution as the listing grade goes up. Any past alterations should have listed building consent behind them. We check all of that before you apply.
The house comes with land. Will the mortgage cover it?
Usually only up to a point. Most residential lenders lend on the home and a limited amount of land, and may give little value to stables, outbuildings or paddocks. Beyond that, or where the land is farmed or let, it becomes a specialist case. Tell us the acreage and how it is used at the start.
Can I get a holiday let mortgage on the Dorset coast?
Yes, but not on a standard buy-to-let mortgage. Holiday-let lenders assess the income across low, mid and high season, usually from a letting agent’s projection, and most want you to already own your own home. More on buy-to-let.
I’m self-employed and my trade is seasonal. Can you help?
Yes. Lenders look at your figures over a whole year, or two, so a quiet winter is not a problem in itself. What matters is how they read your accounts, and that varies between lenders. Our self-employed calculator gives you a guide figure in under a minute.
How much do you charge?
There will be a fee for this advice. The exact amount depends on your circumstances, but we estimate it will be £395 and it is only payable on completion of the loan. The first conversation costs nothing.
Is Help to Buy coming back in Dorset?
A replacement has been announced. Your First Home would offer first-time buyers a 2.5% deposit and a government equity loan of up to 20% on new-build homes in England, with the full details due in the Budget on 28 October 2026. What we know so far, and how it compares with the old Help to Buy.
Talk to a mortgage advisor in Dorset
Wherever you are in the county, leave your name and number and a CeMAP-qualified advisor will call you back from our office in Poole. No long forms, and no pressure.
Darren, Beth, Ben & JakeYour advisors, at our office in Poole
- Rated 5.0 from 160+ Google reviews
- Calls answered in 22 seconds on average
- Open Monday to Saturday, 9am to 5pm