How Much Can I Borrow?
See roughly what lenders could lend on your income, and how they treat each kind of income. An indication only, not an offer of a loan.
Who’s applying?
Your income
Before tax, a year.
Lenders usually count 46 weeks a year, to allow for holidays and gaps between contracts.
From your tax calculations (SA302s) or accounts. Only one year so far? Leave the year before blank.
Share of profit: the company’s net profit after corporation tax, times your shareholding. Some lenders use it instead of your dividends.
Your gross pay before the CIS deduction, less anything paid for materials: lenders only count your labour.
Add any pension, benefits or other income below.
Applicant 2
Before tax, a year.
Lenders usually count 46 weeks a year, to allow for holidays and gaps between contracts.
From your tax calculations (SA302s) or accounts. Only one year so far? Leave the year before blank.
Share of profit: the company’s net profit after corporation tax, times your shareholding. Some lenders use it instead of your dividends.
Your gross pay before the CIS deduction, less anything paid for materials: lenders only count your labour.
Add any pension, benefits or other income below.
Other income Optional
A pension, benefits, maintenance or rental income.
Your deposit and outgoings
An indication only, not an offer of a loan. This calculator gives a general view of what lenders could lend on your income. It isn’t a mortgage offer, an agreement in principle or a decision to lend. What you can actually borrow depends on a full assessment by the lender: your credit history, your outgoings and commitments, your deposit and the property. Using it doesn’t affect your credit score.
Find out what you can actually borrow
Speak with one of our advisors. Leave your name and number and a CeMAP-qualified advisor will call to go through your income and outgoings, and what lenders would actually offer you.
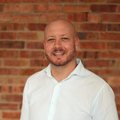
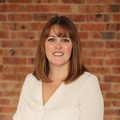
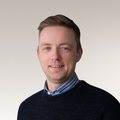
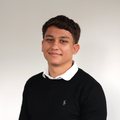
Darren, Beth, Ben & JakeYour advisors, at our office in Poole
- Rated 5.0 from 160+ Google reviews
- Calls answered in 22 seconds on average
- Open Monday to Saturday, 9am to 5pm
How lenders work out what you can borrow
Every lender runs two checks, and the lower answer is what they’ll lend:
- An income multiple. A cap on the loan as a multiple of your income, usually between 4.5 and 5.5 times, depending on the lender, your income and your deposit.
- An affordability check. Your income less your outgoings: credit commitments, childcare, the cost of running a household your size, and a test of whether you could still pay if interest rates rose.
This calculator works on the first. It doesn’t see your outgoings or your credit file, so the figure is an indication of what lenders could lend on your income, not an offer.
The 4.5 times line, and the Bank of England’s limit
Since 2014 the Bank of England has limited lending at 4.5 times income or more to 15% of new mortgages. For most of that time the limit applied to each lender, so lenders rationed their higher multiples and kept 4.5 times as their standard.
That has changed. In July 2025 the Bank’s Financial Policy Committee let individual lenders go over 15%, as long as the market as a whole stays within it. On 14 October 2026 the Prudential Regulation Authority and the FCA confirmed the new rules: from 28 October 2026 the 15% limit applies across the whole market, not to each lender. If the market goes over it, lenders above 15% will be asked to scale back. Retirement interest-only mortgages and further advances aren’t counted.
In practice, more lenders now offer 5 to 6 times income to more people, but each one sets its own rules on who qualifies, and those rules change often.
What multiples lenders use
- Most lenders: around 4.5 times your income as standard, and 4.75 to 5 times with some.
- Higher incomes and bigger deposits: many go to 5 or 5.5 times, often from around £40,000 to £75,000 of income depending on the lender, and usually at 85% loan to value or below.
- 6 times and more: a few lenders, usually for first-time buyers or professionals over an income threshold, or incomes of £100,000 or more. Private banks can go further for very high earners.
The calculator shows 4.75 to 5.5 times your income (5 to 6 times at £100,000 or more): what most people can realistically get from at least some lenders, if their outgoings and credit history fit.
Affordability: why two people on the same salary get different figures
Lenders take your outgoings off your income and check that what’s left covers the mortgage, with room to spare. They look at:
- Credit commitments: loans, car finance and credit cards. Some count part of a card balance even if you clear it each month.
- Childcare and school fees, and any maintenance you pay.
- Your household: how many children and adults depend on you. Lenders use official spending figures for households like yours.
- Student loan and pension contributions, which lower your take-home pay.
- Your credit history: missed payments, defaults or CCJs narrow the lenders and can lower the multiple.
As a rough illustration, at a 7% test rate over 30 years, every £100 a month of loan or card payments is about the same as £15,000 of mortgage. A £300 a month car finance payment could lower what you can borrow by up to about £45,000.
Find out what you can actually borrow
Speak with one of our advisors. We’ll look at your income and your outgoings, and which lenders would lend the most to you.
The “what if rates rise” test
FCA rules say a lender must check you could still afford the payments if interest rates rose over at least the next 5 years. If the rate is fixed for 5 years or more, that test isn’t required, which is why some lenders will lend a little more on a 5-year fix.
Your deposit and loan to value
The bigger your deposit, the lower your loan to value (LTV), and the more lenders will offer their higher multiples. Above 90%, fewer lenders lend and some use a lower multiple. Most lend up to 95%, so with a small deposit, the deposit can set the limit before your income does.
Your age and the term
Many lenders let a mortgage run to age 70 or 75, some later if your income will carry on. A shorter term means higher monthly payments, which can lower what the affordability check allows.
How lenders treat each kind of income
This is where lenders differ most, and where finding the right lender makes the biggest difference.
Employed
- Basic salary: counted in full. Most lenders will lend while you’re on probation; some want it finished.
- Guaranteed allowances (car, shift or location allowances in your contract): usually counted in full.
- Overtime, bonus and commission: most lenders count around half of your average over the last one or two years. Some count all of it if it’s regular and shows on your payslips and P60s.
- A second job: many lenders count it once you’ve had it for 6 to 12 months.
Fixed-term contracts
Employed on a fixed-term contract and paid through PAYE? Lenders use your salary like any other employee’s, but they look at how secure the work is. Many want 12 months left on the contract, or a 12-month record of contract work. With under 2 months left, they’ll want to see the renewal or your next contract. Some accept less, especially if your contracts have been renewed before.
Agency, zero-hours and temporary work
Lenders usually average your pay over the last 12 months, sometimes two years, from your payslips and P60s. A steady record in the same kind of work matters more than the hours in any one week.
Contractors on a day rate
Many lenders work out a contractor’s income from the day rate rather than the accounts: day rate × 5 days × 46 weeks (some use 48). A £450 day rate becomes £103,500 a year. Most want at least 6 months contracting, done or left on your contract, and some want 12 months in total. Contractor mortgages explained.
Self-employed sole traders and partners
Lenders use your net profit, or your share of a partnership’s profit, from your tax calculations (SA302s) and tax year overviews. Most want two years. If your profit has gone up, they average the two years; if it’s gone down, they use the latest. A limited number will lend on one year’s figures. Mortgages with one year’s accounts.
Company directors: dividends or share of profit
Own 20% or more of your company and lenders treat you as self-employed. They work out your income one of two ways:
- Salary plus dividends, the way most lenders do it: averaged over two years, or the latest year if it’s lower.
- Salary plus your share of the company’s net profit after corporation tax: fewer lenders, but it can mean borrowing a lot more if you leave profit in the company. With a £12,570 salary, £40,000 of dividends and a £65,000 share of the profit, that’s £52,570 a year one way and £77,570 the other.
Own less than 20%? Many lenders treat you as employed and use your payslips. We don’t give tax advice: how you pay yourself is one for your accountant. Company director mortgages explained.
CIS subcontractors
Lenders usually use your CIS pay from the last 12 months, or the last 3 months × 4, less anything paid for materials, often without needing your tax returns. CIS mortgages explained.
More than one source of income
Lenders assess each source by its own rules and add them together: a salary with a side business, two part-time jobs, or a job plus rental income. Each part needs its own track record, so a side business usually needs its own accounts before it counts. For self-employed income on its own, our self-employed mortgage calculator shows every method side by side.
Benefits, pensions and other income
- Pensions (state, workplace or private): usually counted in full.
- Child Benefit and Universal Credit: some lenders count them, often only in part. One lender, for example, counts 60% of Universal Credit, leaving out the housing element, as long as one applicant has earned income.
- Disability benefits such as PIP and DLA: accepted by many lenders.
- Maintenance you receive: usually needs a court order or a Child Maintenance Service arrangement, and proof it’s paid.
- Rental income from other property: some lenders count the profit, others ignore it. Buy-to-let mortgages work differently: lenders look at the rent rather than your income. Buy-to-let mortgages.
Ways to borrow more
- Clear or reduce loans and card balances before you apply.
- Put down a bigger deposit: at 85% loan to value or below, more lenders offer higher multiples.
- Take a longer term, within the lender’s age limits.
- Look at a 5-year fix, with lenders that test it more gently.
- Apply with someone else: a joint mortgage, or a joint borrower sole proprietor mortgage, where a family member adds their income without owning the home.
- Pick the right lender for your income. Lenders differ most on bonuses, contracts, self-employed and director income, which is where advice makes the biggest difference.
An indication, not an offer
This calculator gives a general view of what lenders could lend on your income. It isn’t a mortgage offer, an agreement in principle (also called a decision or mortgage in principle) or an offer of a loan. Lenders decide after a full assessment of your income, credit history, outgoings, deposit and the property, and their rules change often. Using the calculator doesn’t affect your credit score, and the figures you type stay in your browser unless you ask us to call you.
Questions people ask
How many times my salary can I borrow?
Most lenders lend around 4.5 times your income, and many go to 5 or 5.5 times for higher incomes and bigger deposits. A few go to 6 times or more. Your outgoings and credit history decide where you land.
Is this a mortgage offer or an agreement in principle?
No. It’s an indication of what lenders could lend on your income. An agreement in principle comes from a lender after it has looked at your details, usually with a credit search. A mortgage offer comes after a full application, with your documents and a valuation of the property.
Does using this calculator affect my credit score?
No. It doesn’t run a credit search, and nothing you type is stored with us unless you ask us to call you.
Do lenders count my bonus or overtime?
Most count around half of your average over the last one or two years. Some count all of it if it’s regular and you can show it on your payslips and P60s. That’s why the calculator shows a range when you add one.
Can I get a mortgage on a fixed-term contract?
Yes. Many lenders want 12 months left on the contract or a 12-month record of contract work, and some accept less if your contracts have been renewed before. Day-rate contractors are usually assessed on day rate × 5 × 46 weeks instead.
Can I borrow 6 times my salary?
Some lenders lend 6 times income, usually to first-time buyers or professionals above an income threshold, or on incomes of £100,000 or more, and usually with a good deposit. Your outgoings still have to fit their affordability check.
Why would two lenders offer me different amounts?
Each lender has its own income multiples, its own affordability model and its own rules for each kind of income. The same person can be offered tens of thousands of pounds more by one lender than another, which is why we compare them for you.
Find out what you can actually borrow
Speak with one of our advisors. A CeMAP-qualified advisor will go through your income and outgoings with you and tell you what lenders would actually offer.
Next step: Our guide for first-time buyers